Our market context
The environment in which we operate has direct implications for our ability to create value, informing our BRIGHT strategy and our investment case. By considering our market context, we are better able to determine our material matters and how best to respond to them.
Political and economic environment
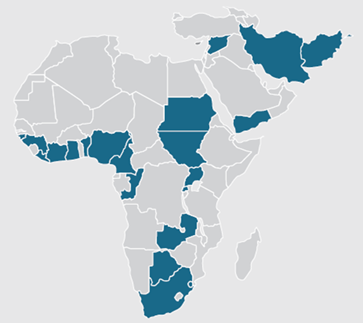
- Prolonged war and conflicts impact Syria, Yemen, Afghanistan and South Sudan.
- Elections planned for 2019 in South Africa and Nigeria.
- Iran remains in focus because of the threat of sanctions from the new US Administration.
- Across our footprint, government interventions are increasing and the regulatory environment is complex but governments are focused on increasing connectivity and digitising societies.
- Global economic growth picking up, but with strong divergence between countries.
- Africa forecast to be world's second fastest growth region to 2020.
- Currency volatility across our main markets.
- Inflationary pressure in Nigeria, Ghana and Iran.
- Growing income and purchasing power in our markets.
- Economies becoming increasingly formalised, improving ease of operation.
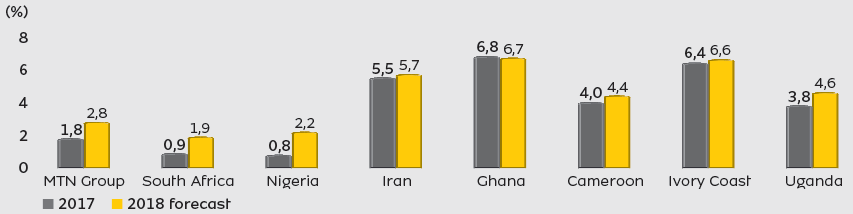
GDP growth
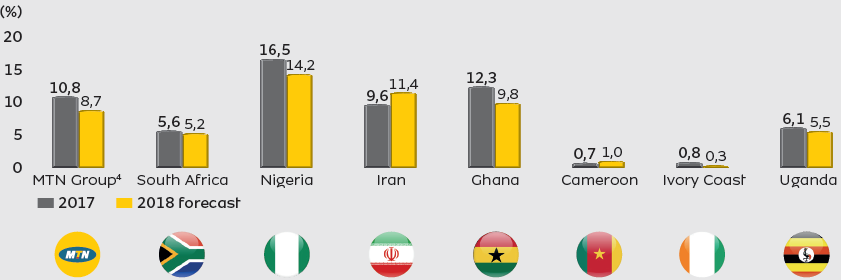
Inflation
Social context
- Young and growing population across our markets.
- Africa urbanising faster than any other region.
- Unemployment remains high.
- Financial inclusion will be key to unlocking consumption.
Forecast population growth1 to 2020
+ 45 million to
700 million
Forecast growth in consumption per capita2 to 2020
+ US$40
to US$1 243
Technology environment
- Low internet adoption.
- Digital connectivity to increase fourfold, with broadband penetration growing from 21% in 2015 to 80% in 2020.
- Exponential data traffic growth.
- MTN Mobile Money ecosystems established in 14 markets.
- 3G and 4G network expansion across all markets.
Forecast data subscriber growth3 to 2020
+ 200 million
to 500 million
Forecast digital subscriber growth3 to 2020
+ 150 million
to 250 million
| 1 | Population across MTN markets |
| 2 | Private consumption per capita is real private consumption at purchasing power parity rates with 2005 base year divided by population for all of MTN's markets except South Sudan (no data available). |
| 3 | MTN market size estimates. Source: IHS World Market Monitor; EIU; WCIS; OVUM; Delta Partners analysis; Kable analysis; MTN analysis. |
| 4 | Weighted average of inflation across MTN Group markets using markets’ GDP contribution as base. |