Annexure 2 - Five-year financial review
2013
US$m |
CAGR1
% |
2013
Rm |
|
| Revenue |
14 135 |
7 |
136 495 |
|
121 867 |
109 834 |
104 500 |
103 295 |
|
| Other income |
143 |
|
1 327 |
|
894 |
1 458 |
– |
– |
|
| Operating expenses |
(8 083) |
7 |
(78 034) |
|
(70 124) |
(61 717) |
(61 220) |
(60 373) |
|
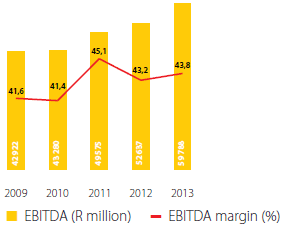
| EBITDA |
6 195 |
9 |
59 788 |
|
52 637 |
49 575 |
43 280 |
42 922 |
|
| Depreciation and amortisation |
(1 992) |
10 |
(19 278) |
|
(15 952) |
(14 032) |
(14 119) |
(13 374) |
|
| Impairment of goodwill |
– |
– |
– |
|
– |
(31) |
(32) |
– |
|
| Operating profit |
4 203 |
8 |
40 510 |
|
36 685 |
35 512 |
29 129 |
29 548 |
|
| Net finance costs |
(118) |
(30) |
(1 234) |
|
(3 790) |
(1 512) |
(3 873) |
(5 284) |
|
| Share of results of associates and joint ventures after tax |
353 |
33 |
3 431 |
|
3 008 |
2 821 |
2 098 |
1 087 |
|
| Profit before tax |
4 438 |
14 |
42 707 |
|
35 903 |
36 821 |
27 354 |
25 351 |
|
| Income tax expense |
(1 283) |
11 |
(12 307) |
|
(11 835) |
(13 034) |
(10 527) |
(8 190) |
|
| Profit after tax |
3 155 |
15 |
30 400 |
|
24 068 |
23 787 |
16 827 |
17 161 |
|
| Profit after tax attributable to |
|
|
|
|
|
|
|
|
|
| – Equity holders of the Company |
2 730 |
16 |
26 289 |
|
20 704 |
20 754 |
14 300 |
14 650 |
|
| – Non-controlling interests |
425 |
13 |
4 111 |
|
3 364 |
3 033 |
2 527 |
2 511 |
|
 |
|
|
|
|
|
|
|
|
|
| Headline earnings |
2 632 |
14 |
25 398 |
|
20 018 |
19 811 |
14 011 |
14 869 |
|
| 1 |
Compound annual growth rate. |
| * |
2012 to 2009 amounts restated to exclude the Group’s proportionate share relating to its interests in joint ventures and to include the inter-entity balances and
transactions previously eliminated on proportionate consolidation. |
| EBITDA |
|
Headline earnings and dividends per share
(cents) |
 |
|
 |
2013
US$m |
CAGR
% |
2013
Rm |
|
| Property, plant and equipment |
8 834 |
11 |
92 903 |
|
73 905 |
64 914 |
57 345 |
61 336 |
|
| Goodwill and intangible assets |
3 590 |
3 |
37 751 |
|
32 594 |
32 672 |
28 518 |
33 997 |
|
| Investments and loans |
1 732 |
15 |
18 212 |
|
12 409 |
11 440 |
9 964 |
10 292 |
|
| Deferred tax assets |
194 |
15 |
2 044 |
|
1 291 |
1 029 |
1 225 |
1 180 |
|
| Bank balances, deposits and cash |
4 344 |
19 |
45 673 |
|
34 565 |
43 458 |
32 933 |
22 846 |
|
| Other current assets |
2 873 |
11 |
30 238 |
|
21 310 |
20 560 |
17 569 |
19 794 |
|
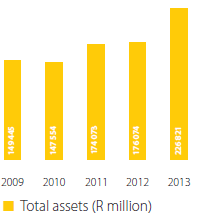
| Total assets |
21 567 |
11 |
226 821 |
|
176 074 |
174 073 |
147 554 |
149 445 |
|
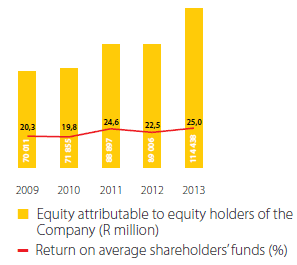
| Equity attributable to equity holders of the Company |
10 881 |
13 |
114 438 |
|
89 006 |
88 897 |
71 855 |
70 011 |
|
| Non-controlling interests |
507 |
17 |
5 333 |
|
3 881 |
3 802 |
2 219 |
2 855 |
|
| Total equity |
11 388 |
13 |
119 771 |
|
92 887 |
92 699 |
74 074 |
72 866 |
|
| Interest-bearing liabilities |
4 377 |
6 |
46 025 |
|
32 084 |
33 208 |
34 454 |
36 268 |
|
| Non-interest-bearing liabilities |
4 597 |
9 |
48 349 |
|
42 392 |
40 200 |
32 043 |
34 703 |
|
| Deferred tax liabilities |
1 205 |
23 |
12 676 |
|
8 711 |
7 966 |
6 983 |
5 608 |
|
| Total liabilities |
10 179 |
9 |
107 050 |
|
83 187 |
81 374 |
73 480 |
76 579 |
|
| Total equity and liabilities |
21 567 |
11 |
226 821 |
|
176 074 |
174 073 |
147 554 |
149 445 |
|
| * |
2012 to 2009 amounts restated to exclude the Group’s proportionate share relating to its interests in joint ventures and to include the inter-entity balances and
transactions previously eliminated on proportionate consolidation. |
| Total assets |
|
Equity and return |
 |
|
 |
2013
US$m |
CAGR
% |
2013
Rm |
|
| Net cash inflows from operating activities |
2 800 |
(2) |
27 025 |
|
20 062 |
23 279 |
28 722 |
29 645 |
|
| Net cash used in investing activities |
(2 055) |
(10) |
(19 835) |
|
(24 212) |
(17 492) |
(13 982) |
(30 242) |
|
| Net cash from/(used in) financing activities |
649 |
43 |
6 264 |
|
(5 280) |
(8 867) |
368 |
1 482 |
|
| Net increase/(decrease) in cash and cash equivalents |
1 394 |
98 |
13 454 |
|
(9 430) |
(3 080) |
15 108 |
885 |
|
| Cash and cash equivalents at beginning of the year |
2 662 |
(3) |
22 539 |
|
33 074 |
32 626 |
20 763 |
24 983 |
|
| Exchange gains/(losses) on cash and cash equivalents |
(293) |
|
3 584 |
|
(1 105) |
3 528 |
(3 245) |
(5 105) |
|
| Cash and cash equivalents at end of the year |
3 763 |
18 |
39 577 |
|
22 539 |
33 074 |
32 626 |
20 763 |
|
| Statement of cash flows – extracts |
|
|
|
|
|
|
|
|
|
| Cash generated from operations |
6 187 |
7 |
59 708 |
|
51 105 |
46 626 |
45 962 |
45 146 |
|
| Dividends paid to equity holders of the Company |
(1 677) |
48 |
(16 187) |
|
(14 919) |
(11 722) |
(6 313) |
(3 381) |
|
| Acquisition of property, plant and equipment |
(2 546) |
(1) |
(24 568) |
|
(20 741) |
(13 191) |
(14 366) |
(25 481) |
|
| * |
2012 to 2009 amounts restated to exclude the Group’s proportionate share relating to its interests in joint ventures and to include the inter-entity cash flows
previously eliminated on proportionate consolidation. |
CAGR
% |
2013 |
|
| Performance per ordinary share |
|
|
|
|
|
|
|
|
| Basic earnings (cents) |
16 |
1 434 |
|
1 126 |
1 119 |
776 |
791 |
|
| Diluted earnings (cents) |
16 |
1 427 |
|
1 120 |
1 111 |
765 |
782 |
|
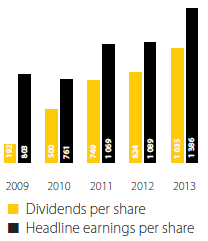
| Headline earnings (cents) |
15 |
1 386 |
|
1 089 |
1 069 |
761 |
803 |
|
| Dividends (cents) |
52 |
1 035,0 |
|
824,0 |
749,0 |
500,0 |
192,0 |
|
| Net asset value – book value (rand)1 |
12 |
61,1 |
|
47,3 |
47,2 |
38,1 |
38,2 |
|
| Returns and profitability ratios |
|
|
|
|
|
|
|
|
| Return on assets (%)2 |
|
20,1 |
|
21,0 |
22,1 |
19,6 |
18,8 |
|
| Return on average shareholders’ funds (%)3 |
|
25,0 |
|
22,5 |
24,6 |
19,8 |
20,3 |
|
| EBITDA margin (%) |
|
43,8 |
|
43,2 |
45,1 |
41,4 |
41,6 |
|
| Adjusted free cash flow (Rm) |
|
29 624 |
|
23 810 |
33 170 |
25 653 |
15 211 |
|
| EBITDA multiple (times)4 |
|
6,8 |
|
6,4 |
5,7 |
5,8 |
4,7 |
|
| Effective taxation rate (%) |
|
28,8 |
|
33,0 |
35,4 |
38,5 |
32,3 |
|
| Solvency and liquidity ratios |
|
|
|
|
|
|
|
|
| Gearing (%)5 |
|
(0,3) |
|
(2,7) |
(11,1) |
2,1 |
18,4 |
|
| Interest cover (times)6 |
|
3,2 |
|
4,3 |
5,7 |
4,8 |
2,5 |
|
| Dividends cover (times)7 |
|
1,3 |
|
1,3 |
1,4 |
1,5 |
4,2 |
|
| Net (cash)/debt to EBITDA8 |
|
– |
|
– |
(0,2) |
– |
0,3 |
|
| Operating cash flow/revenue (%) |
|
43,7 |
|
41,9 |
42,5 |
44,0 |
43,7 |
|
| * |
2012 to 2009 amounts restated to exclude the Group’s proportionate share relating to its interests in joint ventures and to include the inter-entity balances and
transactions previously eliminated on proportionate consolidation. |
| 1 |
Ordinary shareholders’ interest divided by the number of ordinary shares in issue at year end. |
| 2 |
Operating profit as a percentage of the average of the opening and closing balances of total assets. |
| 3 |
Headline earnings as a percentage of the average of the opening and closing balances of ordinary shareholders’ interest. |
| 4 |
Market capitalisation less net (cash)/debt (interest-bearing liabilities less bank balances, deposits and cash) divided by EBITDA. |
| 5 |
Net (cash)/debt as a percentage of total equity. |
| 6 |
Operating profit divided by finance costs. |
| 7 |
Headline earnings divided by total dividend. |
| 8 |
Interest-bearing liabilities less cash, divided by EBITDA. |
CAGR
% |
2013 |
|
| Share statistics |
|
|
|
|
|
|
|
|
| Number of ordinary shares in issue (million) |
|
|
|
|
|
|
|
|
| – at year end |
– |
1 873 |
|
1 883 |
1 885 |
1 885 |
1 841 |
|
| – weighted average during the year |
– |
1 833 |
|
1 838 |
1 854 |
1 842 |
1 851 |
|
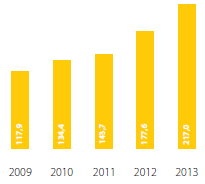
| Closing price (cents per share) |
16 |
21 702 |
|
17 760 |
14 373 |
13 442 |
11 790 |
|
| Market capitalisation (Rm) |
17 |
406 539 |
|
334 507 |
270 904 |
253 318 |
216 999 |
|
| US dollar to rand exchange rates |
|
|
|
|
|
|
|
|
| Average |
4 |
9,65 |
|
8,16 |
7,17 |
7,34 |
8,32 |
|
| Closing |
9 |
10,52 |
|
8,47 |
8,07 |
6,61 |
7,39 |
|
| * |
2012 to 2009 amounts restated to exclude the Group’s proportionate share relating to its interests in joint ventures and to include the inter-entity cash flows
previously eliminated on proportionate consolidation. |
| Market capitalisation (R million) |
|
Closing share price (R) |
 |
|
 |
| Share price performance |
 |
CAGR
% |
|
2013 |
|
| Countries in which MTN has GSM licences (number) |
|
|
21 |
|
21 |
21 |
21 |
21 |
|
| Subscriber numbers (million) |
16 |
|
207,8 |
|
189,3 |
164,5 |
141,6 |
116,0 |
|
| Group entities (excluding joint ventures) |
16 |
|
163,9 |
|
146,4 |
127,5 |
109,7 |
90,9 |
|
| Joint ventures |
15 |
|
43,9 |
|
42,9 |
37,0 |
31,9 |
25,1 |
|
| Countries in which MTN has largest market share (number) |
|
|
15 |
|
15 |
15 |
15 |
15 |
|
| Total number of employees |
(1) |
|
25 424 |
|
26 716 |
24 252 |
26 055 |
26 361 |
|
| Group entities (excluding joint ventures) |
(4) |
|
22 476 |
|
23 871 |
21 504 |
23 594 |
24 553 |
|
| Joint ventures |
|
|
2 948 |
|
2 845 |
2 748 |
2 461 |
1 808 |
|
| CO2 emissions from energy use (tonnes) |
28 |
|
1 525 542 |
|
1 040 723 |
950 564 |
1 127 254 |
565 861 |
|
| Operational information |
|
|
|
|
|
|
|
|
|
| South Africa |
|
|
|
|
|
|
|
|
|
| Mobile penetration (%) |
|
|
135 |
|
131 |
120 |
105 |
103 |
|
| Market share (%) |
|
|
35 |
|
38 |
34 |
36 |
32 |
|
| Subscribers (million) |
13 |
|
26 |
|
25 |
22 |
19 |
16 |
|
| ARPU (ZAR)1 |
(4) |
|
108 |
|
122 |
134 |
154 |
126 |
|
| EBITDA margin (%) |
|
|
34 |
|
35 |
35 |
34 |
31 |
|
| Capex/revenue (%) |
|
|
15 |
|
16 |
11 |
11 |
18 |
|
| Nigeria |
|
|
|
|
|
|
|
|
|
| Mobile penetration (%) |
|
|
69 |
|
62 |
54 |
49 |
42 |
|
| Market share (%) |
|
|
49 |
|
48 |
50 |
52 |
50 |
|
| Subscribers (million) |
16 |
|
57 |
|
47 |
42 |
39 |
31 |
|
| ARPU (US$)1 |
(10) |
|
7 |
|
9 |
10 |
11 |
12 |
|
| EBITDA margin (%) |
|
|
61 |
|
58 |
62 |
63 |
59 |
|
| Capex/revenue (%) |
|
|
30 |
|
36 |
18 |
14 |
31 |
|
| Nigerian naira average foreign exchange rate |
(2) |
|
16,46 |
|
19,50 |
21,76 |
20,67 |
17,83 |
|
| Nigerian naira closing foreign exchange rate |
(7) |
|
15,23 |
|
18,47 |
20,10 |
23,00 |
20,29 |
|
| Ghana |
|
|
|
|
|
|
|
|
|
| Mobile penetration (%) |
|
|
99 |
|
91 |
78 |
67 |
61 |
|
| Market share (%) |
|
|
50 |
|
51 |
52 |
53 |
55 |
|
| Subscribers (million) |
13 |
|
13 |
|
12 |
10 |
9 |
8 |
|
| ARPU (US$)1 |
(7) |
|
6 |
|
6 |
7 |
7 |
8 |
|
| EBITDA margin (%)2 |
|
|
38 |
|
37 |
37 |
44 |
45 |
|
| Capex/revenue (%) |
|
|
20 |
|
16 |
14 |
54 |
46 |
|
| Ghanaian cedi average foreign exchange rate |
6 |
|
0,21 |
|
0,23 |
0,21 |
0,20 |
0,17 |
|
| Ghanaian cedi closing foreign exchange rate |
3 |
|
0,22 |
|
0,22 |
0,20 |
0,22 |
0,19 |
|
| Iran |
|
|
|
|
|
|
|
|
|
| Mobile penetration (%) |
|
|
114 |
|
113 |
103 |
92 |
80 |
|
| Market share (%) |
|
|
47 |
|
47 |
45 |
44 |
40 |
|
| Subscribers (million) |
16 |
|
41 |
|
41 |
35 |
30 |
23 |
|
| ARPU (US$)1 |
(16) |
|
4 |
|
7 |
8 |
8 |
8 |
|
| EBITDA margin (%) |
|
|
43 |
|
44 |
43 |
41 |
35 |
|
| Capex/revenue (%) |
|
|
18 |
|
9 |
11 |
18 |
44 |
|
| Iranian rial average foreign exchange rate |
21 |
|
2 554 |
|
1 686 |
1 474 |
1 401 |
1 195 |
|
| Iranian rial closing foreign exchange rate |
15 |
|
2 356 |
|
2 905 |
1 378 |
1 566 |
1 354 |
|
| Syria |
|
|
|
|
|
|
|
|
|
| Mobile penetration (%) |
|
|
81 |
|
59 |
58 |
50 |
46 |
|
| Market share (%) |
|
|
44 |
|
45 |
46 |
45 |
45 |
|
| Subscribers (million) |
11 |
|
6 |
|
6 |
6 |
5 |
4 |
|
| ARPU (US$)1 |
(27) |
|
5 |
|
9 |
14 |
16 |
18 |
|
| EBITDA margin (%) |
|
|
17 |
|
23 |
26 |
24 |
20 |
|
| Capex/revenue (%) |
|
|
28 |
|
11 |
7 |
6 |
11 |
|
| Syrian pound average foreign exchange rate |
25 |
|
13,57 |
|
8,34 |
6,54 |
6,39 |
5,59 |
|
| Syrian pound closing foreign exchange rate |
22 |
|
13,67 |
|
10,22 |
6,71 |
7,13 |
6,20 |
|
| Cameroon |
|
|
|
|
|
|
|
|
|
| Mobile penetration (%) |
|
|
69 |
|
62 |
54 |
40 |
39 |
|
| Market share (%) |
|
|
59 |
|
56 |
55 |
60 |
61 |
|
| Subscribers (million) |
22 |
|
9 |
|
7 |
6 |
5 |
4 |
|
| ARPU (US$)1 |
(14) |
|
5 |
|
6 |
7 |
8 |
9 |
|
| EBITDA margin (%)2 |
|
|
43 |
|
46 |
44 |
49 |
51 |
|
| Capex/revenue (%) |
|
|
15 |
|
19 |
10 |
16 |
23 |
|
| Cameroon Communaute Financière Africaine franc average foreign exchange rate |
(2) |
|
51,96 |
|
62,20 |
65,67 |
67,26 |
56,58 |
|
| Cameroon Communaute Financière Africaine franc closing foreign exchange rate |
(8) |
|
45,23 |
|
58,70 |
62,73 |
74,20 |
61,89 |
|
| Ivory Coast |
|
|
|
|
|
|
|
|
|
| Mobile penetration (%) |
|
|
79 |
|
77 |
75 |
64 |
51 |
|
| Market share (%) |
|
|
38 |
|
36 |
37 |
38 |
38 |
|
| Subscribers (million) |
15 |
|
7 |
|
6 |
6 |
5 |
4 |
|
| ARPU (US$)1 |
(6) |
|
7 |
|
6 |
6 |
7 |
9 |
|
| EBITDA margin (%)2 |
|
|
41 |
|
40 |
42 |
33 |
29 |
|
| Capex/revenue (%) |
|
|
15 |
|
22 |
12 |
24 |
28 |
|
| Côte d’Ivoire Communaute Financière Africaine franc average foreign exchange rate |
(3) |
|
51,50 |
|
62,31 |
64,81 |
67,43 |
57,08 |
|
| Côte d’Ivoire Communaute Financière Africaine franc closing foreign exchange rate |
(8) |
|
45,23 |
|
58,70 |
62,73 |
76,07 |
61,89 |
|
| Uganda |
|
|
|
|
|
|
|
|
|
| Mobile penetration (%) |
|
|
44 |
|
41 |
42 |
34 |
25 |
|
| Market share (%) |
|
|
54 |
|
53 |
52 |
56 |
63 |
|
| Subscribers (million) |
16 |
|
9 |
|
8 |
8 |
6 |
5 |
|
| ARPU (US$)1 |
(10) |
|
4 |
|
4 |
4 |
5 |
6 |
|
| EBITDA margin (%)2 |
|
|
36 |
|
36 |
35 |
45 |
44 |
|
| Capex/revenue (%) |
|
|
12 |
|
13 |
26 |
21 |
34 |
|
| Uganda shilling average foreign exchange rate |
2 |
|
264,66 |
|
303,08 |
347,60 |
295,99 |
242,29 |
|
| Uganda shilling closing foreign exchange rate |
(2) |
|
239,81 |
|
312,26 |
306,73 |
348,03 |
256,43 |
|
| Sudan |
|
|
|
|
|
|
|
|
|
| Mobile penetration (%) |
|
|
73 |
|
73 |
53 |
39 |
34 |
|
| Market share (%) |
|
|
34 |
|
32 |
27 |
21 |
28 |
|
| Subscribers (million) |
22 |
|
9 |
|
8 |
6 |
3 |
4 |
|
| ARPU (US$)1 |
(21) |
|
2 |
|
3 |
5 |
5 |
5 |
|
| EBITDA margin (%) |
|
|
32 |
|
28 |
22 |
17 |
20 |
|
| Capex/revenue (%) |
|
|
43 |
|
62 |
49 |
41 |
34 |
|
| Sudanese pound average foreign exchange rate |
15 |
|
0,50 |
|
0,43 |
0,36 |
0,34 |
0,29 |
|
| Sudanese pound closing foreign exchange rate |
14 |
|
0,54 |
|
0,52 |
0,33 |
0,40 |
0,32 |
|
| 1 |
Annual ARPU. |
| 2 |
Excluding profit on tower sales. |
|
|